

Enterprise fintech has an AI problem. Enthusiasm for AI in finance is far ahead of real deployment.
Across industries, and especially in financial services, executives say artificial intelligence is strategically important. Boards talk about it constantly, and investor decks present it as a central pillar of future growth. Product roadmaps put it near the top.
Look at day-to-day operations, though, and the picture changes. Executives want AI, but they use it a lot less than you’d think. Consider these statistics:
- 79% of global executives report some familiarity with generative AI, but only 22% report using it regularly in their work, and even fewer (7%) report fully scaling AI across workflows (source).
- 79% of organizations report running AI pilots or limited deployments. Only about 25% to 30% report scaling AI across multiple business units or enterprise workflows (source).
Lack of investment doesn’t explain the gap. Organizations are putting money into AI at an unprecedented rate, and industry research projects global AI spending to reach hundreds of billions of dollars a year over the next several years (source). Capital, talent and infrastructure are all moving toward the technology. Even so, many AI initiatives never get past the experimental stage.
A recognizable adoption pattern in enterprise
For anyone building enterprise financial technology, this gap looks familiar. The same pattern shows up with almost every major technology shift.
Enthusiasm peaks during the demo. In a controlled environment, with clean data, ideal configuration and a clear use case, new capabilities look compelling. Stakeholders see faster workflows, cleaner outputs and fewer manual steps.
Connect the same system to real infrastructure and real financial processes, and things change. Data is inconsistent, integrations behave unpredictably, and edge cases appear quickly. Something that looked effortless in the demo becomes much harder to run day to day.
Operational friction kills adoption faster than bad technology does. As many as 85% of AI projects fail to deliver their expected outcomes, often because organizations struggle with data readiness, system integration and operational workflows rather than with the limits of the AI models themselves (source).
Financial systems add another layer of skepticism. Unlike consumer AI tools, fintech platforms run inside high-stakes workflows: financial reporting, incentive compensation payouts, regulatory compliance, risk management, and systems that feed into the wider financial markets. Even small errors can have material consequences.
As a result, finance leaders judge automation differently from most software users. Before they trust a system, it has to show that it works and that its outputs can be understood, verified and explained in the context of real financial decisions and risk assessment.
Put simply, AI adoption in fintech is mostly a trust problem.
The trust barrier: why AI fails in high-stakes workflows
In fintech, a tool gets adopted when its results hold up under scrutiny. Working most of the time isn’t enough.
Finance leaders are trained to minimize risk. Only 14% of CFOs completely trust AI technology to deliver accurate accounting data on its own (source). That hesitation comes from the job itself. Every output that touches financial reporting, compensation or compliance has to be defensible.
This is where many AI systems break down. Even when the answer is right, they often can’t show how they got there, and where auditability matters, a black-box output meets resistance immediately.
The stakes raise the bar further. The tolerance for error in financial workflows is effectively zero. A model that gets something mostly right isn’t useful if it affects payroll, commission pay or reporting. Until AI systems can meet that standard and show work that is clear, explainable and verifiable, they won’t be adopted in the workflows that matter most.
AI fails in fintech because it starts at the end
Financial workflows need trust, and most teams introduce AI at exactly the point where trust is hardest to earn.
Most AI efforts in fintech target final outputs such as commission calculations, forecasts, payouts and reporting. The reasoning seems sound. These are complex, structured problems, so they should benefit most from automation and AI.
But those outputs sit at the very end of major workflows. That’s where numbers turn into payments, reports and decisions with financial and regulatory consequences.
Putting AI there means asking it to work under maximum scrutiny on day one, before it has built any trust and before users understand how it reaches its answers. Nobody tolerates ambiguity at that stage, so even a system that works well faces the highest possible bar from the start.
When these projects stall, the cause is usually placement rather than complexity. Teams start AI in the one part of the workflow where the organization won’t accept any risk.
AI gets adopted when it preserves human control
There’s a simpler explanation for why some systems get adopted and others don’t. People trust a system when they can see how it makes decisions and step in when they need to.
In enterprise environments, and in finance especially, users don’t want to hand over control. They’re responsible for the outcome, and if something goes wrong, they’re the ones held accountable. Any system that takes away their ability to validate, adjust or override a decision meets resistance right away.
This is where many AI implementations miss the mark. They try to automate decisions end to end, when users want to move faster without giving up control.
Research points the same way. A study from MIT Sloan suggests AI is more likely to complement human workers than to replace them (source).
The systems that succeed keep people involved. They help people make the decisions they already own, faster and with more confidence.
The shift: where AI actually works
If adoption depends on trust, control and placement, the implication follows. AI should start at the point of friction, well before the point of decision.
Instead of automating final outcomes, aim AI at the work that leads up to them: setup, configuration, data structuring and integration. That work slows teams down, but it doesn’t carry the same level of risk.
AI has a different adoption profile here. The outputs still matter, but they aren’t final. People can review, adjust and validate them before anything moves downstream, which lowers the expectation from perfect to useful.
In this model, the AI’s job is to get you to a usable starting point much faster, and people stay responsible for the answer. Positioned that way, as a way to speed up the work instead of replacing judgment, AI meets far less resistance. The system earns trust by making the work easier, instead of asking for it up front.
What good AI looks like in fintech
If this shift is real, it should show up in how a system behaves on day one. In practice, good AI in finance looks like this:
- It starts with a structured commission model or plan instead of a blank slate.
- It generates plan components and logic from existing data.
- It identifies data relationships across CRM, ERP and payroll without manual mapping.
- It flags errors with a clear root cause and a suggested fix.
- It produces outputs that people can review and adjust before anything is finalized.
Here’s how AI shows up in Variabl specifically:
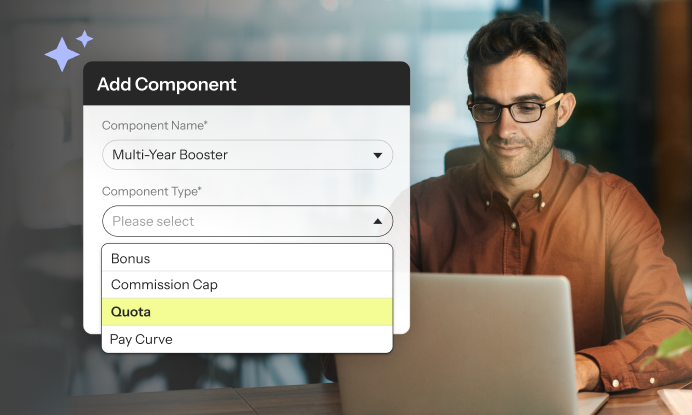
- AI-assisted plan configuration using effective-dated rules and reusable components.
- Automated data structuring across integrated systems with a no-code data manager (and SQL when you prefer or need it).
- Guided query generation and transformation for complex compensation logic.
- Built-in validation, audit trails and versioning to support reviews and approvals.
- Workflow support for approvals, disputes and statement distribution.
None of this replaces ownership. Finance and RevOps teams still review, adjust and approve everything before it’s finalized. The system produces a usable starting point that people can change, which keeps auditability and control intact while removing the slowest parts of the process.
The effect is immediate. Instead of spending weeks getting a system into a usable state, teams can move from raw data to a configured plan in a fraction of the time. People still make the decisions. The manual work of getting to them is what goes away.
The lesson for enterprise builders and AI adopters in finance
Enterprise teams don’t adopt AI all at once. They adopt it one trusted use case at a time.
The turning point is rarely a big strategic decision. More often it’s a small operational moment, when the system saves real time on a task and makes it easy to check what it did. That’s what changes behavior.
In fintech, that matters more than ambition. Teams don’t need AI to do everything. They need it to do something useful, clearly, with the right level of oversight. Once that happens consistently, usage spreads until the system is simply part of the workflow.
Most teams miss this. Adoption depends less on how advanced the system is than on how quickly it proves its value in a way users can understand, check and repeat.
The difference between AI that gets demoed and AI that gets used
Everyone wants AI in fintech, but very few teams use it in the workflows that matter. We’ve been building in this space for years, and that gap doesn’t surprise us. What holds teams back is usually how the technology is applied.
Systems built for the demo are optimized for capability. They try to automate the most complex, highest-stakes decisions from day one, look impressive in the evaluation, and get switched off once they meet real data and real accountability.
The systems that get used show up earlier in the workflow and take friction out of it. They make the work easier without taking control away from the people responsible for the outcome, and they earn their place in the workflow.
That’s the approach we’re taking with sales compensation software at Variabl. We use AI to speed up judgment, starting with the setup and data work that comes before the final numbers, and we expect the platform to earn trust at each step instead of asking for it up front.
If you’re evaluating AI for a finance workflow, ask the vendor to run it on your messiest data and to show you where a person can review and override each output. How a tool handles that tells you more about whether your team will use it than the demo does.